Quick answer
Gambling payment processing lands in the high-risk category for four reasons that stack on top of each other: legality that changes by jurisdiction, elevated chargeback and fraud exposure, card-network rules that require extra registration and monitoring, and federal rules that force banks to block unlawful internet gambling transactions. Licensed operators in lawful markets can still get approved, but most processors decline the category outright, and the ones that say yes will underwrite carefully. Confirm licensing, network, and legal questions with your acquiring partner and counsel before you apply.
What You Should Know Before You Start
Why do most processors decline gambling merchants?
- Card networks and banks treat gambling as a high-brand-risk category, which adds registration, monitoring, and liability that many processors would rather avoid.
- Chargeback rates in gambling tend to run higher than in standard retail, and a bad dispute ratio can threaten the processor’s own standing with the networks.
Does a license guarantee approval?
- No. A valid license covering the markets you serve usually acts as the entry ticket to underwriting, not the finish line.
- Acquiring banks still review processing history, financials, ownership, and compliance controls before deciding.
Can a U.S. business accept online gambling payments?
- Only where the activity is lawful in the state or tribal jurisdiction where the bet is placed, and only through a payment provider willing to support that activity.
- Federal rules require banks and card systems to block payments tied to unlawful internet gambling, so legality drives everything that follows.
What will underwriting ask for?
- Licensing documents, processing statements, bank statements, ownership details, KYC and AML procedures, and a clear picture of where your players live.
- Expect questions about how you segregate player funds from operating money and how you handle withdrawals.
Gambling payment processing frustrates more operators than almost any other high-risk category, because the business can be fully legal, fully licensed, and still get turned away by a dozen providers in a row. The decline usually has nothing to do with the quality of your operation and everything to do with how banks, card networks, and regulators score the risk. This guide explains that scoring, what underwriters actually review, and how licensed gambling operators can approach high-risk merchant accounts with realistic expectations.
Table of Contents
- Why Is Gambling Payment Processing Classified as High Risk?
- How Gambling Regulations and Jurisdiction Shape Merchant Account Approval
- What a Gambling Merchant Account Covers: Online Casino, Sports Betting, Poker Rooms, and Lotteries
- Chargebacks, Dispute Ratios, and Fraud Controls for Gambling Merchants
- What Underwriters and Acquiring Banks Review for High-Risk Businesses in Gambling
- Choosing a High-Risk Payment Gateway for Player Deposits and Withdrawals
- How Long Does Gambling Merchant Account Approval Take?
- Fees, Rolling Reserves, and Settlement Terms Gambling Operators Should Expect
Why Is Gambling Payment Processing Classified as High Risk?
The high-risk label reflects how underwriters score exposure, not a judgment about your business or your customers. Gambling merchants tend to trip several risk factors at once, and each one on its own can push an application into the high-risk lane.
- Legality by jurisdiction: a bet that is lawful in one state or country can be unlawful a few miles away, which complicates any processor operating across borders.
- Chargeback exposure: a player who loses money has a built-in motive to dispute the charge, and card-not-present deposits make friendly fraud easier to attempt.
- Card-network rules: Visa treats certain categories as high brand risk and requires acquirers to register those merchants and apply enhanced safeguards, as described on its Network Integrity page.
- Money-laundering scrutiny: gambling platforms move large sums quickly, so banks expect strong KYC and AML controls before they touch the account.
The size of the legal market makes the friction more frustrating. U.S. commercial gaming produced a record $78.72 billion in gross gaming revenue in 2025, up 9.2 percent from the prior year, according to the American Gaming Association. Plenty of legitimate money moves through this industry, and most of it still has to fight for a stable merchant account.
Good to Know: The Unlawful Internet Gambling Enforcement Act, implemented through Regulation GG, requires card systems, ACH operators, and other payment participants to maintain policies designed to block payments tied to unlawful internet gambling. That rule is a big reason banks screen gambling applicants so hard at account opening.
How Gambling Regulations and Jurisdiction Shape Merchant Account Approval
Every gambling merchant account conversation starts with one question: where are your players, and is the activity lawful there? Gambling regulations vary by country, state, and region, and a license only helps if it covers the markets where you actually process payments.
- In the United States, sports betting and online casino play are regulated state by state and through tribal compacts, and the AGA tracked 38 commercial gaming markets in 2025.
- Operators serving players in Great Britain need an operating license from the UK Gambling Commission, regardless of where the business is based.
- Many operators serving European players hold a license from the Malta Gaming Authority, which acquiring banks in that region widely recognize.
- Sweepstakes and skill-based platforms often sit in a gray area that acquirers evaluate case by case, and their treatment is changing quickly in several U.S. states.
Underwriters will match your license status against your player geography. A mismatch, such as accepting international players your license does not cover, tends to end the application. Confirm your licensing footprint with gaming counsel before you submit anything to a processor.
What a Gambling Merchant Account Covers: Online Casino, Sports Betting, Poker Rooms, and Lotteries
Gambling merchants are not one homogeneous group in an underwriter’s eyes. Underwriters separate casino, sportsbook, and poker activity, and they also distinguish between different types of online gaming, since each vertical carries its own risk profile and acquiring banks price and monitor them differently.
| Vertical | Typical risk drivers | What underwriters watch |
|---|---|---|
| Online casino | High deposit velocity, instant deposits, frequent disputes after losses | License scope, player geography, dispute ratio, fund segregation |
| Sports betting | State-by-state legality, event-driven volume spikes | Geolocation controls, state licensing, processing history |
| Poker rooms | Player-to-player fund movement, collusion and laundering exposure | KYC depth, AML monitoring, withdrawal controls |
| Lotteries and sweepstakes | Shifting legal definitions, prize and refund disputes | Legal opinions, terms and conditions, marketing claims |
Online casino play grew fastest of any legal U.S. vertical in 2025, with revenue up 27.6 percent, while sports betting revenue climbed 22.8 percent, per the AGA. Fast growth in a category often attracts tighter monitoring rather than looser terms, since acquirers know where the next wave of disputes will come from.
Chargebacks, Dispute Ratios, and Fraud Controls for Gambling Merchants
Chargebacks sit at the center of gambling payment processing risk. A player who loses a deposit can call their card issuer and claim they never authorized the charge, and card-not-present transactions give the merchant little physical evidence to fight back with.
The stakes for dispute ratios rose again this year. The Visa Acquirer Monitoring Program lowered its excessive threshold for merchants to 1.5 percent on April 1, 2026, and enrolled merchants pay $8 per disputed or fraudulent transaction, according to the Merchant Risk Council. A gambling merchant that drifts over that line can pull its acquirer over the acquirer’s own threshold, which explains why processors watch this category so closely.
- Real-time fraud screening at the deposit stage helps catch stolen card details before a bet is placed.
- 3D Secure 2.0 authentication can shift liability for certain fraud disputes back to the card issuer and reduce friendly fraud claims.
- Monitoring tools that flag unusual betting behavior, rapid deposit patterns, or bonus abuse help operators act before disputes pile up.
- Clear billing descriptors, responsive customer service, and a documented refund policy give you evidence when you do fight a chargeback.
Our chargeback prevention tips apply directly here, and operators should also understand how a high dispute ratio can get an account canceled and how the MATCH list can follow a terminated merchant to the next application.
Watch Out: Never describe a gambling business as something else on a merchant application or route deposits through an unrelated account to dodge scrutiny. Miscoding a gambling merchant violates card-network rules, usually ends in termination, and can land the owners on the MATCH list for years.
What Underwriters and Acquiring Banks Review for High-Risk Businesses in Gambling
Underwriting for gambling merchants goes deeper than a standard retail file. Acquiring banks want to see that the operator understands its own risk and already controls it, rather than promising to build controls after approval.
What most acquiring banks ask gambling applicants to provide
- ✓ Valid gaming licenses covering every market where you accept player deposits
- ✓ Three to six months of processing statements showing volume, refunds, and dispute counts
- ✓ Business bank statements and proof that player funds sit apart from operating cash
- ✓ Written KYC, AML, age-verification, and responsible-gaming procedures
- ✓ Ownership and beneficial-owner details for every principal
- ✓ PCI DSS compliance evidence for how you handle card data
Underwriters also commonly review the operator’s website for visible responsible-gaming, KYC and AML, and policy disclosures, so keep those pages current before you apply.
Processing history carries real weight. An operator with six clean months at another provider walks in with proof that its risk controls work. A startup without history can still get reviewed, but expect the bank to lean harder on reserves, lower initial volume caps, and tighter monitoring until a track record exists.
Pro Tip: Keep player funds in a segregated account from day one and document the process. Underwriters treat fund segregation as a sign of a serious operator, and several licensing bodies require it anyway.
Choosing a High-Risk Payment Gateway for Player Deposits and Withdrawals
A standard gateway built for retail checkouts rarely holds up in gambling, so gateway selection should account for the acquiring bank and the payment processor behind it. A gambling site needs stable processing and fraud controls that match its licensing footprint. A high-risk payment gateway for this industry needs to handle instant deposits, fast withdrawals, multiple currencies, and layered fraud screening without breaking the player experience.
- Support for credit and debit cards plus alternative payment methods, since some card issuers block gambling transactions entirely and players need a backup option.
- Bank-to-bank options such as ACH payment processing for U.S. players, which can lower dispute exposure compared with cards.
- Multi-currency settlement for operators serving international players under an appropriate license.
- Built-in 3D Secure 2.0, velocity limits, device fingerprinting, and geolocation checks tied to your licensing map.
- Automated compliance reporting that feeds your AML and regulatory obligations rather than adding manual work.
Cryptocurrency deposits have become more common in the gambling sector, particularly offshore, but acceptance depends entirely on your license terms, your bank’s appetite, and local law. Treat crypto as a question for counsel and your acquirer, not a workaround for card declines. For a checklist on evaluating gateway security in general, see our guide on how to tell a payment gateway is secured.
How Long Does Gambling Merchant Account Approval Take?
There is no honest fixed answer. Some providers advertise turnaround measured in days, but gambling files routinely take longer because the bank has more to verify. Timelines depend on how complete your documentation is, whether your license covers every market you serve, and how quickly the acquiring bank moves on high-brand-risk registrations.
- A complete file with clean processing history and unambiguous licensing tends to move fastest.
- Missing documents, unclear player geography, or a prior termination usually add weeks rather than days.
- Pre-approval from a provider and final approval from the acquiring bank are two different milestones, and only the second one lets you process.
Ask any provider to explain what “approved” means in their process and which bank actually makes the call. A merchant account approval that skips network registration for a high-risk category can turn into a termination later, which costs far more than a slower, properly registered start.
Fees, Rolling Reserves, and Settlement Terms Gambling Operators Should Expect
Transaction fees for gambling merchants typically run higher than standard retail rates, and the account usually comes with a rolling reserve. That is the acquiring bank pricing in the chargeback exposure and the regulatory workload, not a penalty aimed at you personally.
- Rolling reserves hold back a percentage of processing volume for a set period to cover future disputes, with terms that vary by bank and by your history.
- Chargeback fees accumulate quickly in this industry, so the per-dispute cost matters as much as the headline rate.
- Settlement can run on a delayed schedule at first, with faster funding often available once the account shows stable performance over several business days and months.
- Monthly fees, gateway fees, registration fees, and currency conversion costs all belong in your comparison, not just the discount rate.
We recommend asking for every fee and reserve term in writing before you sign, and confirming with counsel that the settlement structure fits your licensing obligations around player funds. Terms that look expensive on paper are sometimes the ones that keep the account open.
Why First Card Payments
We have spent more than 20 years placing merchants that other providers turn away, across regulated and high-risk industries, with acquiring partners that actually understand the risk. Our relationships with more than 30 banks and ISOs give us room to look at a gambling file on its own merits, subject to each partner’s criteria, applicable law, and the operator holding a valid license for every market it serves, so gambling operators can keep their focus on running the business while we guide the payment processing and underwriting steps.
We will tell you plainly if a partner in our network cannot support your model, and we will not suggest disguising the business to get through. Where a fit exists, we walk you through underwriting, reserves, fees, and network registration before you commit, and we stay involved after approval with ongoing service to help protect the account’s long-term health. That same approach serves the adult, CBD, nutraceutical, travel, online dating, continuity subscription, debt relief, and credit repair merchants we support from our offices in Miami, Florida, and Los Angeles, California.
Talk to our team at 877.441.6801 or start your application to find out whether a licensed gambling operation fits one of our partner programs.
Explore More Payment Resources
Operators new to the category should read why high chargeback rates can get a merchant account canceled and our overview of what payment fraud looks like before building a deposit flow. Both pieces pair well with the chargeback and gateway guidance above.
Beyond payment processing, First Card Payments also connects clients with Nextiva business phone services and a referral partnership program for consultants and agencies who refer merchants our way. You can learn more about our team on our About Us page, including Alexander Ellis’s background, browse more guides on our blog, or head to our homepage to see the full range of services we offer. All high-risk industries we serve are listed on our high-risk merchant accounts page, and you can reach our team directly through our contact page.
Licensed and tired of being declined?
Tell us about your operation, your licenses, and your markets, and we will give you a candid read on whether a partner fit exists before you apply today.
Frequently Asked Questions
Why is gambling considered high risk by banks and card networks?
Gambling combines several risk factors that underwriters score heavily: legality that shifts by jurisdiction, elevated chargeback rates from players disputing losses, card-not-present fraud exposure, and money-laundering scrutiny. Card networks classify the category as high brand risk and require extra registration, so banks carry more liability when they approve a gambling merchant.
Can I get a gambling merchant account without a license?
Realistically, no. Acquiring banks require a valid license covering every market where you accept player deposits, and federal rules oblige U.S. payment systems to block payments tied to unlawful internet gambling. Getting licensed and confirming your legal footprint with gaming counsel comes before any merchant account application.
Is online sports betting legal in the United States?
Sports betting is regulated state by state and through tribal compacts rather than under a single federal rule, so legality depends on where the bet is placed. Operators need state licensing and geolocation controls that keep wagers inside lawful jurisdictions. Confirm your position with counsel, since state rules continue to change.
What chargeback ratio will get a gambling merchant account shut down?
Card networks set the ceiling. Visa’s monitoring program treats a merchant ratio of 1.5 percent or more as excessive as of April 2026, and acquiring banks often impose stricter internal limits on gambling merchants to protect their own standing. Ask your provider what internal threshold applies to your account, since it may sit well below the network figure.
What is a rolling reserve, and why do gambling accounts have one?
A rolling reserve is a percentage of your processing volume that the acquiring bank holds for a set period, typically to cover future chargebacks and refunds. Gambling accounts almost always carry one because of the dispute exposure. The percentage and hold period vary by bank and usually loosen as your account builds a stable history.
Do I need a special payment gateway for an online casino?
Most online casino operators need a gateway built for high-risk categories rather than a standard retail gateway. That means support for instant deposits and withdrawals, multiple currencies, 3D Secure 2.0, real-time fraud screening, and reporting that feeds your compliance obligations. Confirm the gateway integrates with your licensing and geolocation requirements before committing.
Can international players deposit through a U.S. merchant account?
Only if your license covers those players’ jurisdictions and your acquiring bank supports cross-border settlement in the relevant currencies. Many operators serving international players use separate accounts or providers for different regions rather than one account for everything. Your acquirer and counsel should sign off on the structure before you go live.
How do sweepstakes and social casino platforms fit into gambling payment processing?
Sweepstakes and social casino models often sit in a gray area, and several U.S. states have moved to restrict or redefine them recently. Acquiring banks typically ask for a legal opinion and review the terms, prize structure, and marketing before deciding. Expect these platforms to face the same scrutiny as any other form of gambling payment processing, even where the operator considers the model a promotion rather than a wager.
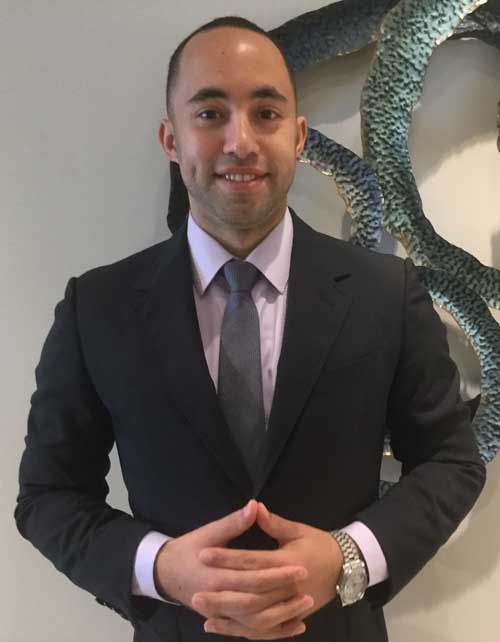
My interest in the financial world started to blossom in High School. However, my parents tell me I use to watch financial programs before the age of 5. So, I guess I was born with the Financial bug. In high school I was accepted into their Finance Academy, which I attended for 4 years. In addition to graduating high school, I accumulated a substantial amount of financial knowledge few people experience at such a young age. During which time, I won the State of Florida Stock Market Contest and I also finished in the top 100 in the CNBC stock market contest which had over 1 million participants throughout the country (including some of Wall Street’s elites) with a take home prize of $1 million. These achievements allowed me to be invited to many shows and events with top people in their fields of business from around the world.