Quick answer
Merchant account processing for high risk businesses almost always starts with the same core paperwork: a signed application, a government photo ID, business formation documents, a voided check or bank letter, and three to six months of bank statements. Underwriters may also ask for processing statements, licenses, financial reports, and a chargeback prevention plan. Exact lists vary by acquiring bank, so confirm the final checklist with your provider before you apply.
Documents in hand already? Skip straight to underwriting prep.
What you should know about merchant account processing before you start
Can you get a high risk merchant account with poor credit history?
- Often yes. Underwriters weigh your full risk profile, not just a credit score.
- Processing history, chargeback records, business model, and industry all factor in.
- A low score usually means closer review, not an automatic decline.
How long does the approval process take?
- High risk applications commonly take about 7 to 10 days, sometimes longer.
- Complete, organized documents shorten the timeline more than anything else.
- Pre approval and final approval differ, so ask your provider which stage you have reached.
Will you pay more than low risk businesses?
- Usually. Transaction rates often land between 3% and 10%, per our high risk fees and rates guide.
- Rolling reserves of 5% to 20% of volume appear in many agreements.
- Read every fee line before signing so hidden fees never surprise you.
Do you need processing history to apply?
- No. New businesses can apply, though underwriters treat them as elevated risk.
- Strong bank statements and a clear business plan help offset a short track record.
- Expect conservative volume caps at first, with room to grow later.
Merchant account processing (sometimes called merchant processing) starts with underwriting, and the high risk merchant account requirements behind it confuse a lot of business owners. A decline or sudden termination can make a high risk merchant account from a specialist feel out of reach. Drawing on more than 20 years of placing high risk merchants, this guide covers every document underwriters actually review and how to prepare a file that gets read favorably.
Table of contents
- Why underwriters treat your business as high risk
- High risk merchant account requirements: the core document checklist
- Financial documents underwriters review for high risk accounts
- Processing history and chargeback records for high risk merchants
- Extra paperwork for regulated high risk industries
- How underwriters review high risk businesses for merchant account processing
- Hidden fees and reserve terms to check before you sign
- Choosing an account provider that fits your business needs
Why underwriters treat your business as high risk
Banks call a business high risk when its financial and compliance exposure runs above their comfort level. The label reflects underwriting math, never a judgment about you as a business owner. Your documents exist to answer the questions behind that math.
Common reasons a business gets deemed high risk include:
- Chargeback ratios above 1% of transactions, the level where card networks start watching
- Recurring billing and subscription services, which attract friendly fraud
- Card not present sales through an online store, mobile apps, or phone orders
- High dollar amounts per ticket or high transaction volumes each month
- Regulatory scrutiny in fields like CBD, nutraceuticals, debt relief, or credit repair
- A young company under two years old with no proven track record
- International transactions and multi currency sales
Stakes keep rising across payment processing. Global card fraud losses reached $33.41 billion in 2024, according to the Nilson Report [1]. Underwriters read your file with that backdrop in mind, so a complete document package works in your favor from page one.
Good to Know: A high risk classification does not block you from accepting electronic payments. It changes which acquiring banks will review your file and what terms they offer. If you only recently learned you count as high risk, the right paperwork puts you back in control.
High risk merchant account requirements: the core document checklist
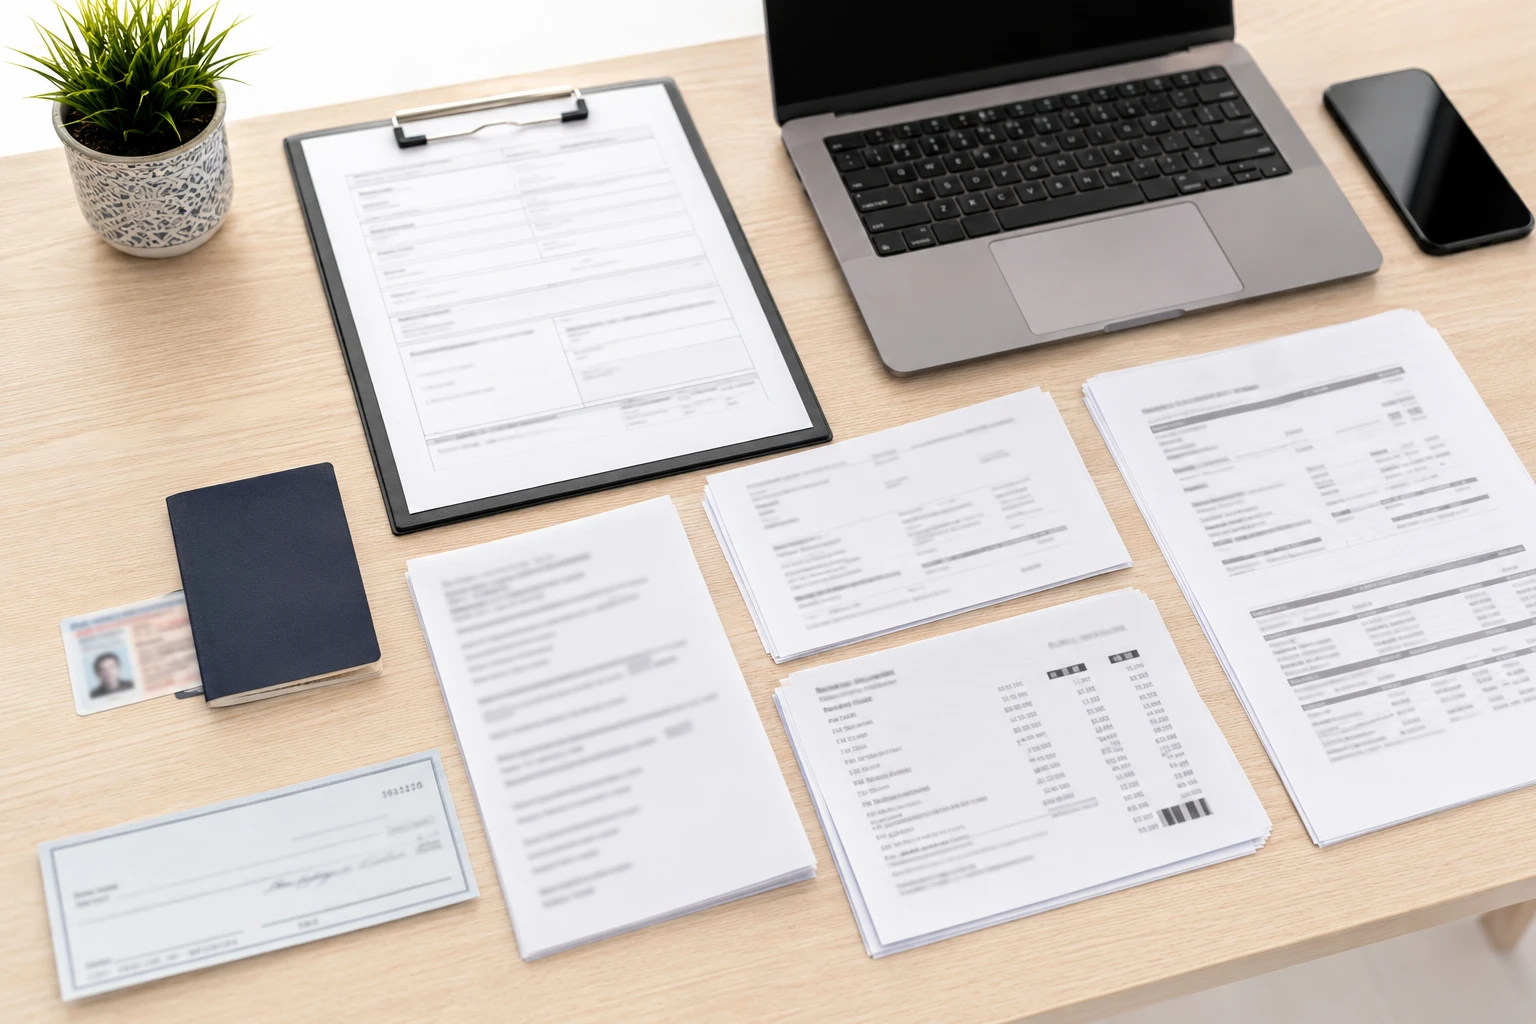
Nearly every acquirer starts with the same foundation. Gather these before you touch the application and the rest of the approval process moves faster.
Core document checklist
- ✓ Signed merchant application from your payment processor or merchant services provider
- ✓ Government photo ID for every owner, which supports anti-money laundering checks
- ✓ Business formation documents, such as articles of incorporation or an LLC certificate
- ✓ EIN letter from the IRS confirming your tax identity
- ✓ Voided check or bank letter tying your deposit account to the business
- ✓ Three to six months of business bank statements
- ✓ Three to six months of processing statements, when you have them
- ✓ A working website or clear description of services offered and products sold
Legal identity verification sits at the center of this list. Acquirers must follow anti-money laundering rules, so mismatched names, addresses, or tax IDs stall files fast. Check every document against your formation records before you send the file.
Financial documents underwriters review for high risk accounts
Money tells the story underwriters trust most. Bank statements, financial statements, and tax returns show whether your cash flow can absorb refunds, chargeback fees, and a reserve without missing payroll.
Expect requests for some or all of the following:
- Recent business bank statements showing steady deposits and healthy balances
- Profit and loss statements or a balance sheet for established companies
- Business or personal tax returns for larger monthly volume requests
- Personal credit consent, since underwriters assess owner credit in high risk files
- Projected monthly volume, average ticket, and highest expected ticket
Poor credit history rarely kills an application on its own. Strong balances and consistent sales trends can offset a weak score. If you carry both bad credit and a high risk business type, prepare thicker documentation and expect closer review. Our guide on opening a merchant account with bad credit covers that scenario in depth.
Pro Tip: Ask your bank for statements as original PDFs instead of scans or screenshots. Clean, unaltered files clear fraud screening faster and signal that you run an organized operation.
Processing history and chargeback records for high risk merchants
Processing statements from your previous payment service providers matter as much as bank records for high risk merchants. They reveal your real transaction patterns, refund rate, and chargeback ratio, the exact numbers a new acquirer must live with.
The bar keeps moving here. Since April 1, 2026, Visa counts fraud reports and disputes together under its Visa Acquirer Monitoring Program. The excessive threshold now sits at 1.5% for merchants in the US. The Merchant Risk Council notes the change “narrows the margin for error” for businesses with elevated dispute activity [2]. Underwriters now read chargeback records with that tighter standard in mind.
Strengthen this part of your file with:
- Statements from every processor you used in the past six months, including any that terminated you
- A short written explanation for excessive chargebacks or refund spikes, with dates and fixes
- A chargeback prevention plan covering fraud tools, chargeback alerts, and how you monitor transactions
- Evidence of clear billing descriptors, refund policies, and customer service response times
Honesty wins here. Underwriters can see MATCH list placements and terminations, so disclose them upfront and explain your risk management fixes. As our guide to chargeback suspensions puts it, a ratio above 1% “will put the merchant on the card associations’ watch list.” Our chargeback prevention tips can help you build a credible plan.
Watch Out: Never hide a past termination or dress up your business model to look low risk. Underwriters verify everything, and concealment leads to freezes, terminations, and MATCH placement that follows you for years.
Extra paperwork for regulated high risk industries
Certain high risk industries carry document requirements on top of the core checklist. Regulators and card networks expect proof that you operate legally, and acquirers pass those expectations to you.
Common industry additions include:
- Licenses and registrations, such as state credit services registration for credit repair merchant accounts
- Lab reports and compliant labeling for CBD merchant accounts and nutraceutical merchant accounts
- Seller of travel registrations and supplier agreements for travel agency merchant accounts
- Age verification and content controls for adult entertainment merchant accounts, plus card network registration where required
- Clear terms, cancellation flows, and billing disclosures for continuity subscription merchant accounts and online dating merchant accounts
- Program compliance documentation for debt relief merchant accounts
Requirements shift as laws and card network rules change. Confirm the current list with your acquiring partner, and bring legal questions to qualified counsel rather than relying on a blog post, including this one.
How underwriters review high risk businesses for merchant account processing
Once your file lands, underwriters score it across several angles at once. Understanding their lens helps you present high risk businesses in the strongest accurate light.
The review typically covers:
- Business model and website match, so what you sell matches what you told the bank
- Financial health, including balances, cash flow stability, and debt load
- Owner background, credit, and any past MATCH placements
- Chargeback exposure based on industry, ticket size, and delivery timelines
- Volume request against your history, since a big jump raises questions
Some of our partners can turn a pre-approval around in 24 to 48 hours, while full underwriting on a strong file typically wraps within 7 to 10 business days. Thin files trigger follow up questions that stretch timelines to weeks.
Respond to underwriter requests the same day when possible, because stale applications drift to the bottom of the queue. Our guide to faster merchant account approval shows how prepared merchants shorten the wait.
Good to Know: Pre approval and final approval differ. Pre approval signals that a partner wants your file. Final approval comes after full underwriting, and gateway setup follows that. Ask which stage you have reached before you count on going live.
Hidden fees and reserve terms to check before you sign

Approval feels like the finish line, but the agreement you sign decides what merchant account processing actually costs you. High risk accounts commonly carry transaction rates between 3% and 10%, a monthly fee, and sometimes a rolling reserve, as we detail in our guide to high risk merchant account fees and rates. None of that should hide in fine print.
Before signing, verify:
- The full rate structure, whether tiered, interchange plus, or a flat fee model
- Rolling reserves, where the acquirer withholds 5% to 20% of processing volume against future chargebacks
- Common fees for statements, PCI compliance [3], gateways, batch processing, and chargeback handling
- Long term contracts, early termination charges, and automatic renewal clauses
- Volume caps and what happens when you exceed them
Reserves protect the bank, yet they also lock up working capital. Model your cash flow with the reserve in place before you commit, since payroll and inventory wait for no one.
Our breakdown of the true cost of a high risk merchant account shows where merchants get surprised. Pairing card payments with ACH payment processing can also improve cash flow on large invoices.
Pro Tip: Ask every prospective account provider one question in writing: what would make you freeze or terminate this account? The quality of that answer tells you more than any rate quote.
Choosing an account provider that fits your business needs
Documents get you through underwriting. The right merchant services partner keeps your merchant account processing running for years. Match the account provider to your business needs, not just to the lowest advertised rate.
Look for a partner who can:
- Place your business type with acquirers who actually want your industry
- Let you accept payments everywhere you sell, in store, online, and through mobile apps
- Support how customers pay, from debit cards to Apple Pay and other digital wallets
- Explain payment gateways, integrations, and how to track sales across channels
- Stand behind you when disputes, reviews, or volume changes hit the account
A provider who understands your customer base and the challenges high risk businesses face will ask hard questions early. Treat that as a good sign. Easy promises upfront often turn into frozen funds later.
Why First Card Payments for high risk merchant account processing
We built First Card Payments around one idea: merchants deserve a candid guide through underwriting, not a sales pitch. Our team brings more than 20 years of high risk merchant services experience and relationships with more than 30 banks and ISOs. That network lets us match your file to acquirers suited to your industry instead of forcing one template on every business.
Here you can read about our company and our president, Alexander Ellis. From our offices in Miami, Florida, and Los Angeles, California, we help eligible low risk and high risk merchants across many industries prepare the strongest accurate application.
We walk you through requirements, fees, reserves, and tradeoffs before you sign anything. After approval, we stay involved to protect long term account health.
Approval always depends on underwriting, your business model, your paperwork, and each partner’s rules. What we promise instead of guarantees: straight answers, organized preparation, and an advocate in your corner. Call us at 877.441.6801, contact our team, or start your application review when your documents come together.
Frequently asked questions
What credit score do you need for a high risk merchant account?
There is no set minimum. Many traditional processors prefer stronger personal credit, while high risk specialists weigh it as one factor among many. Processing history, bank balances, and business model can outweigh a weak score. Expect a personal credit check as a standard part of underwriting for owners.
How long does high risk underwriting take?
Most complete files clear in about 7 to 10 business days. Missing documents, unexplained chargebacks, or license questions can stretch that to several weeks. Fast, complete responses to underwriter questions keep your file moving. Ask your provider for a realistic timeline based on your industry before you apply.
Why do underwriters want three to six months of bank statements?
Bank statements prove your cash flow can survive refunds, disputes, and a reserve. Underwriters want to see steady deposits, money in the bank, and no overdrafts. Statements also show that the revenue you claimed matches real life. Clean records here often offset weaknesses elsewhere in the file.
Can a new business with no processing history get approved?
Yes, though underwriters often treat young companies as elevated risks, especially under two years of operating history. A clear business plan, strong personal financials, and realistic volume projections carry the file instead. Expect conservative caps and possibly a reserve at first. A clean first six months of processing opens the door to better terms.
Can you get a merchant account after a MATCH list placement?
Sometimes, depending on the reason for placement and how you fixed the underlying problem. Disclose the placement upfront with a written explanation and evidence of corrective steps. Some acquirers in our network review MATCH files case by case. Concealing a placement almost always ends in termination once discovered.
What does a rolling reserve mean for my cash flow?
With a rolling reserve, the acquirer withholds a percentage of your volume, often 5% to 20%, and releases each portion after a set period defined in your agreement, often around six months. The money remains yours, but you cannot spend it yet. Budget as though that revenue arrives late. Reserves often shrink after months of clean processing.
Do high risk merchants always pay higher fees?
Higher fees come standard, often 3% to 10% per transaction, because acquirers price for elevated risk. Rates vary widely by industry, volume, and history, so compare offers rather than accepting the first quote. A proven track record of low disputes gives you leverage to renegotiate. Watch the full fee schedule, not just the headline rate.
Can I speed up the approval process?
Preparation beats everything else. Submit every document on the checklist in one organized package, answer follow ups the same day, and make sure your website matches your application. Explain any bad history before the underwriter finds it on their own. Working with a specialist who knows which acquirer fits your industry also removes wasted attempts.
What should I do if my application gets declined?
Ask for the reason, because declines usually trace to fixable issues like missing licenses, thin financials, or an acquirer that simply avoids your industry. Fix the gap, then reapply through a partner with better matched banking relationships. One decline does not define your business. Many merchants we work with found approval after several rejections elsewhere, once a complete file reached the right desk and their merchant account processing finally moved forward.
Keep building your knowledge
Start with our overview of high risk merchant accounts to see every industry we serve. Then browse the First Card Payments blog for fresh guides on underwriting, chargebacks, and payment strategy.
Consultants and agencies who refer merchants can learn about compensation and process through our referral partnerships page. Many of our merchants also cut communication costs with Nextiva business phone services. Ready to move? Apply today and our team will review your options with you.
Sources
- Nilson Report: Global Card Fraud Losses Reach $33.41 Billion
- Merchant Risk Council: Stricter VAMP Ratio Thresholds and Compliance, 2026
- PCI Security Standards Council: Merchant Resources
Ready to put your documents to work?
Gather your checklist, then let our team match your business with acquiring partners who understand your industry. Straight answers, no pressure, and support that continues after approval.
My interest in the financial world started to blossom in High School. However, my parents tell me I use to watch financial programs before the age of 5. So, I guess I was born with the Financial bug. In high school I was accepted into their Finance Academy, which I attended for 4 years. In addition to graduating high school, I accumulated a substantial amount of financial knowledge few people experience at such a young age. During which time, I won the State of Florida Stock Market Contest and I also finished in the top 100 in the CNBC stock market contest which had over 1 million participants throughout the country (including some of Wall Street’s elites) with a take home prize of $1 million. These achievements allowed me to be invited to many shows and events with top people in their fields of business from around the world.